The Compliance Checklist Every New UAE Company Skips, and Regrets
Starting a company in the UAE is an exciting milestone, but receiving a trade license is only the beginning. During the UAE business setup process, entrepreneurs often concentrate on registration, banking, and launching operations. What happens afterward deserves equal attention. Business setup in UAE involves ongoing corporate compliance requirements that can affect a company’s ability to operate smoothly. Missing important registrations, maintaining outdated information, or overlooking renewal dates can create unnecessary administrative problems. This checklist explains the essential areas every new company should monitor to stay organized and meet its responsibilities.
1. Keep Your Company and Registration Records Updated
Accurate business registration records are essential for managing a company effectively. Businesses should maintain updated copies of their trade license, incorporation documents, registered address, and approved business activities.
These documents may be requested by banks, government authorities, and business service providers.
Founders should regularly review their regulatory documentation to ensure it reflects their current operations. Changes involving the business address, legal structure, or registered activities may require formal updates.
Monitoring trade license validity is equally important. Keep digital backups of important company records and establish a straightforward filing system that makes documents accessible whenever needed.
2. Track Ownership and Management Information
Company ownership and management details should never be treated as paperwork that becomes irrelevant after incorporation.
Businesses must maintain accurate beneficial ownership records, including information about the individuals who ultimately own or control the company, where applicable.
Organized shareholder records and director records also help establish clear management responsibilities and ownership structures.
When shareholders, directors, or controlling individuals change, businesses should determine whether updated ownership disclosures or notifications to the relevant authority are required.
Maintaining this information consistently supports transparency and makes it easier to respond to banking checks, regulatory enquiries, and future changes in company structure.
3. Do Not Overlook Corporate Tax Requirements
Corporate tax responsibilities are among the most important obligations new companies should assess.
Founders should determine whether corporate tax registration is required and identify the filing rules applicable to their legal entity.
Importantly, operating within a free zone does not automatically remove all corporate tax responsibilities. Businesses should verify their tax treatment under the applicable regulations.
Maintaining accurate accounting records supports tax calculations, return preparation, and regulatory reviews.
Companies should also monitor compliance deadlines and confirm whether annual tax returns or other declarations are necessary.
Checking guidance from the Federal Tax Authority helps businesses understand their responsibilities rather than assuming that newly established companies are automatically exempt.
4. Check Whether VAT Registration Applies to Your Business
Not every newly established company must immediately register for VAT. However, businesses should regularly assess their taxable supplies and imports to determine when VAT registration becomes necessary.
For UAE-resident businesses, mandatory registration generally applies when taxable supplies and imports exceed AED 375,000 over the previous 12 months or are expected to exceed that amount within the next 30 days.
Different provisions may apply to certain non-resident businesses.
Companies should maintain transaction details, invoices, and supporting documents for effective financial record keeping.
Once registered, businesses must understand their VAT return requirements and related regulatory reporting responsibilities.
Reviewing turnover regularly helps identify potential obligations before registration deadlines are missed.
5. Build Proper Accounting Records From Day One
One common mistake among new entrepreneurs is postponing bookkeeping until the business generates substantial revenue.
However, reconstructing financial information months later can be time-consuming and unreliable.
Companies should maintain organized accounting records covering sales invoices, supplier payments, operating expenses, bank transactions, and other relevant financial activities.
A consistent system for financial record keeping can simplify tax preparation, audits, banking enquiries, and management decisions.
Using suitable accounting software or professional bookkeeping support can also improve accuracy.
Businesses should retain supporting documents for the periods required under applicable laws, even when their transaction volumes are relatively small.
6. Monitor License Renewals and Annual Filing Obligations
Obtaining a business license does not mean it remains valid indefinitely.
Companies should establish a system for monitoring license renewal dates, registration requirements, and any approvals that have separate validity periods.
Depending on the company’s structure and licensing authority, annual filing obligations may include financial statements, declarations, registration updates, or other required submissions.
Businesses should identify which statutory filings apply to their circumstances instead of assuming every company follows the same process.
A shared compliance calendar can help management prepare documentation and complete payments before deadlines.
Regular reviews also reduce the risk of overlooking requirements during busy operating periods.
7. Review Approvals Before Expanding Business Activities
Business growth often involves introducing additional products, expanding services, or entering new markets.
However, an existing trade license may not automatically authorize every new activity.
Before expanding, companies should check whether their proposed operations fall within the activities permitted by their licensing authority.
Certain sectors may also require additional business activity approvals from specialized regulatory bodies.
For example, activities involving healthcare, financial services, or regulated commercial operations may have requirements beyond general company licensing.
Businesses should review their licenses and complete any necessary amendments or statutory filings before launching new activities.
This approach helps avoid interruptions and unnecessary compliance complications.
A Simple Monthly Compliance Check for New Companies
Compliance monitoring does not need to be complicated. A short monthly review can help business owners identify missing information and upcoming responsibilities.
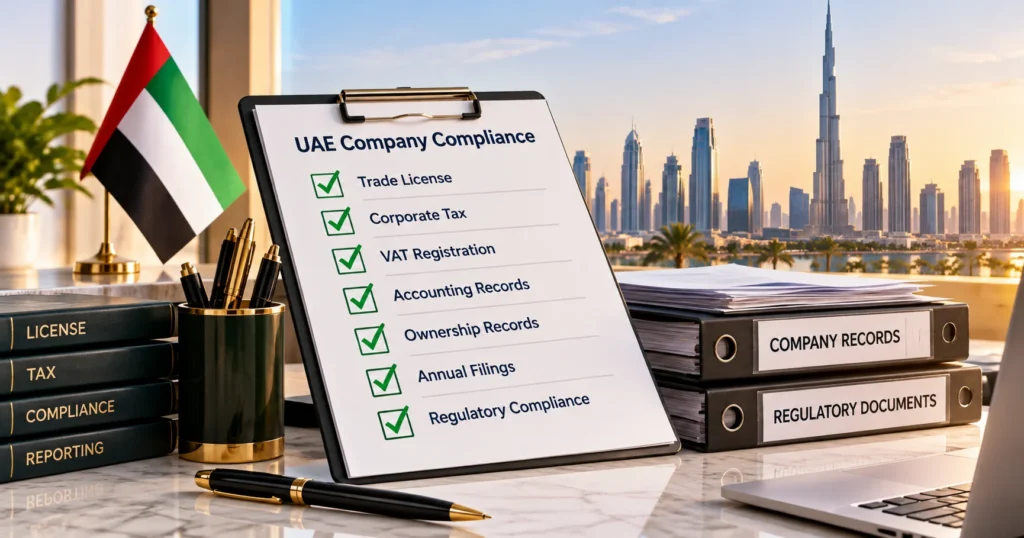
Use this practical checklist:
- License status: Confirm that your trade license and relevant permits remain valid.
- Company information: Check ownership, management, and registration details for changes.
- Corporate tax: Review applicable registration, filing, and payment obligations.
- VAT position: Monitor taxable turnover and any required VAT submissions.
- Accounting documents: Ensure invoices, expenses, and bank transactions are properly recorded.
- Upcoming deadlines: Check renewals, declarations, and other scheduled submissions.
- Regulatory documents: Verify that important certificates and supporting information are current.
Assigning responsibility for these checks helps ensure that important tasks are not overlooked.
Where appropriate, founders can also seek guidance from qualified accountants or compliance professionals.
Conclusion
Running a compliant company requires more than completing the initial registration process. New UAE businesses should treat compliance as an ongoing management responsibility rather than paperwork addressed only when problems arise.
Maintaining accurate records, understanding tax obligations, monitoring renewals, and reviewing regulatory requirements can help businesses operate more confidently.
Regular checks also make it easier to identify responsibilities whenever ownership, business activities, or operational arrangements change.
The most practical approach is to establish a clear compliance process early, assign responsibility for essential tasks, and review requirements consistently.
Good preparation today can make everyday business administration significantly easier tomorrow.